In the current economic climate, conducting business requires embracing digital payment methods. Customers, accustomed to the convenience of cards and mobile wallets, bypass cash only vendors, making reliable payment acceptance a necessity for revenue generation. For the merchant, however, this seamless customer experience comes at a price: the payment processing fee. Understanding the exact breakdown of this fee, and how different providers structure it, is paramount for maintaining healthy profit margins and ensuring financial predictability.
The Components of Every Card Charge
A single transaction fee is far from monolithic; it is a blend of several distinct costs. Primary among these are the Interchange Fees, paid to the bank that issued the customer’s card, and Scheme Fees, paid to the card network (such as Visa or Mastercard). Finally, there is the Acquirer Markup, the fee charged by the payment processor itself for facilitating and securing the transaction. The variability of Interchange and Scheme Fees, influenced by factors like card type (consumer debit versus corporate credit) and whether the transaction is domestic or cross border, is what makes a uniform, simple rate challenging to achieve.
Decoding Variable Transaction Charges
Businesses must look beyond headline figures when evaluating their payment partner’s offering. The effective cost of accepting card payments, encompassing the full range of operational expenses is best understood by analyzing the teya card machine rates provided under different membership plans. These rates, which are often provided as a simple, blended percentage for consumer cards, are critical for accurate profit forecasting. Businesses with different turnover volumes can choose a plan tailored to their needs, ranging from a higher transaction percentage with no monthly commitment to significantly lower percentages tied to a fixed monthly fee, providing a predictable cost structure based on anticipated sales volume.
The Efficiency of Tiered Membership Plans
To address the diverse needs of the merchant landscape, from small startups to high volume retail operations, modern payment providers offer stratified membership models. The “Pay As You Go” structure, with zero monthly fee but a slightly higher per transaction rate, serves new or seasonal businesses with low, unpredictable card turnover. Conversely, established businesses with consistent, significant sales volumes benefit greatly from premium tiers that charge a modest monthly subscription in exchange for a sharply reduced percentage rate on every transaction, leading to substantial savings once a certain revenue threshold is reached.
Transaction Rates Versus Total Service Value
While the transaction percentage is the most immediate factor influencing cost, a holistic evaluation requires assessing the total value proposition. Many contemporary payment solutions eliminate or absorb fees that were traditionally charged separately by legacy providers, such as fees for PCI compliance, authorization fees, or charges for online bank transfers. Furthermore, the inclusion of a complimentary business account, often accompanied by next day or even instant settlement capabilities, is a massive value add, improving cash flow and reducing reliance on external, potentially costly, banking services.
The Role of Integrated Financial Ecosystems
Forward thinking payment services extend their utility far beyond merely processing transactions. By integrating the payment terminal with a business account, they create an efficient financial ecosystem. This often includes features like a business debit card that offers cashback on spending, providing a tangible, recurring financial benefit back to the merchant. The presence of such integrated tools demonstrates a commitment to not just taking payments, but actively assisting the client in managing and growing their business capital.
Transparency in Fee Calculation
A crucial element of a trustworthy payment partnership is fee transparency. Whether a provider uses a simple blended rate or a more granular Interchange++ model, the merchant must be able to clearly identify the total cost applied to each sale. The blended rate is valued for its predictability, while the Interchange++ model is appreciated by high volume businesses for its cost granularity, allowing them to see the exact fees charged by the card networks and issuers. Regardless of the model, the final invoice should be clear, detailed, and easily reconcilable with daily sales data.
The Significance of Contract Flexibility
Many businesses have suffered under restrictive, multi year contracts imposed by older payment processors. A key feature of competitive modern offerings is the freedom from rigid contractual lock ins. The flexibility to scale services up, down, or even to move providers without incurring substantial early termination penalties is a significant commercial advantage. This commitment to non binding agreements demonstrates confidence in the service quality, allowing the business to adapt to market fluctuations without unnecessary contractual liability.
Advanced Features for Operational Enhancement
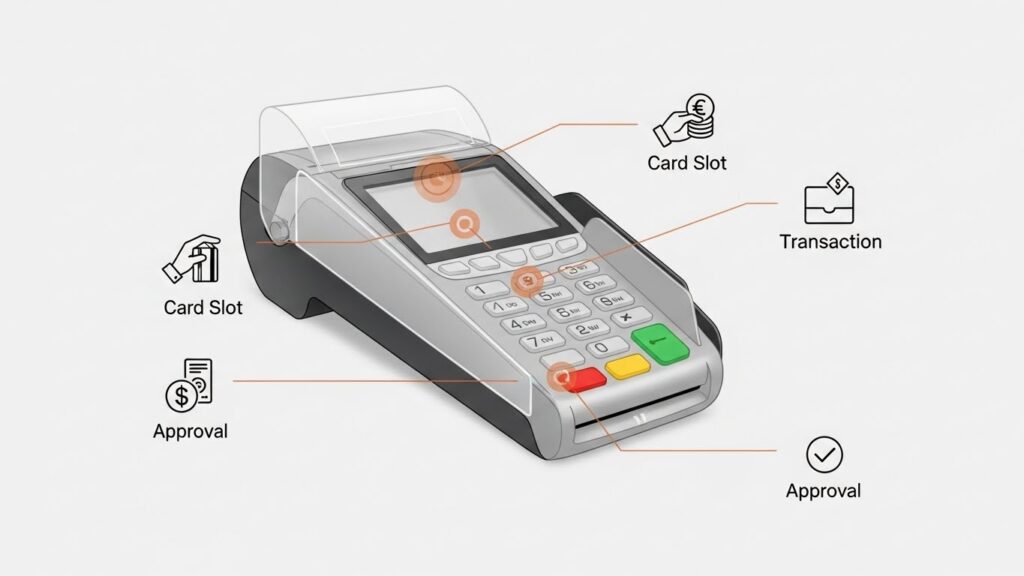
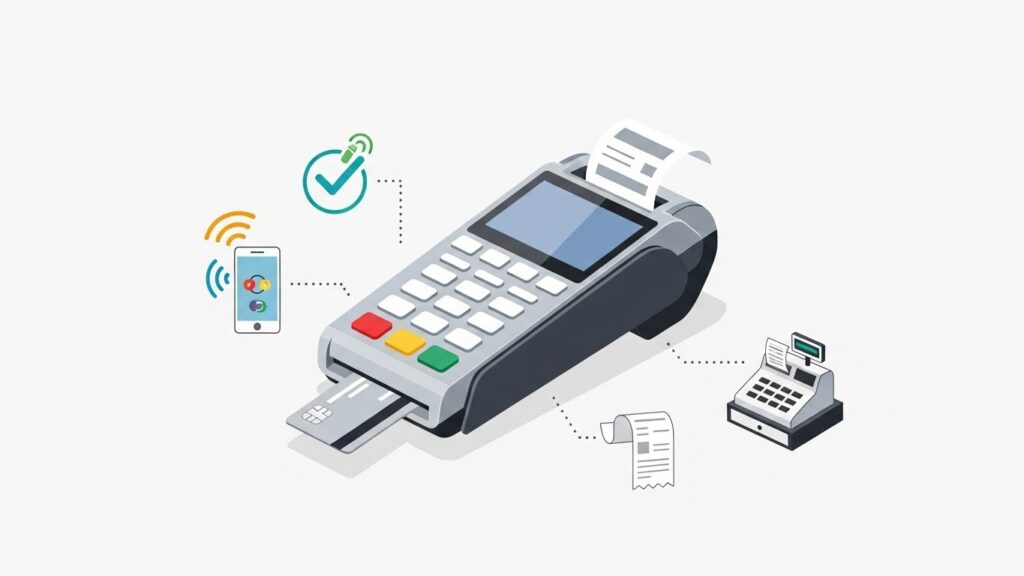
The functionality of the payment terminal hardware itself contributes to long term efficiency. Devices with excellent battery life, intuitive Android operating systems, and integrated receipt printers reduce friction at the point of sale. Features such as on device tip handling, split payment capabilities, and seamless integration with existing Electronic Point of Sale (EPoS) software further enhance operational flow. These technological advantages minimize transaction errors and speed up service, ultimately supporting higher customer throughput and sales volume.
Conclusion: A Decision Based on Commercial Fit
Selecting the appropriate payment processing solution necessitates a careful, analytical assessment of the business’s specific needs against the provider’s pricing structure. By closely comparing the teya card machine rates across different membership tiers, assessing the value of bundled services like the business account and fast settlements, and insisting on contract flexibility, a business can select a payment partner that provides optimal cost efficiency. The best choice is the one that minimizes transaction expense while maximizing functional reliability and supporting sustainable, profitable business growth.